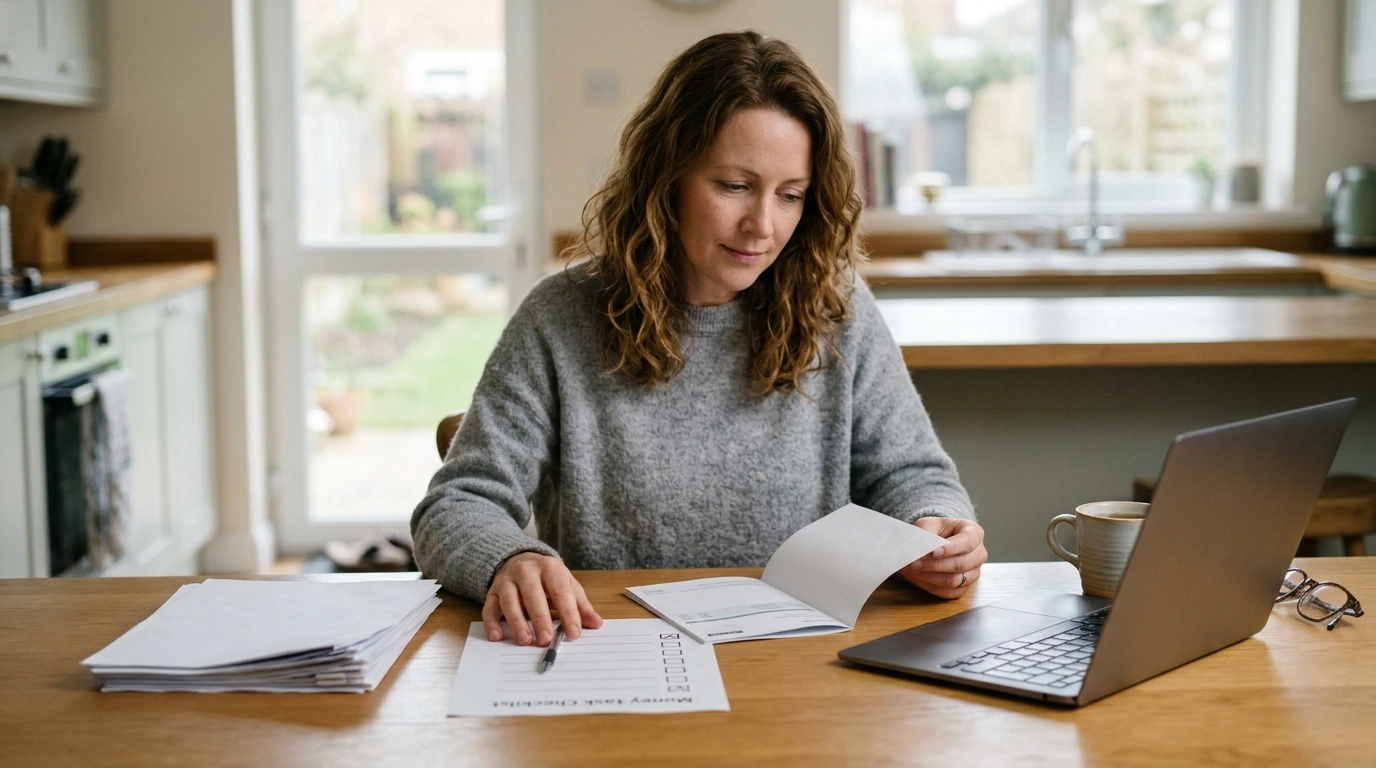
A bank balance, bill, or purchase decision can become more than a routine task when uncertainty feels hard to tolerate. You may need to verify a detail, but you may also feel pulled to verify it again after you already have the answer. Our approach is to give everyday money tasks a clear purpose and stopping point. The goal is not perfect certainty; it is a workable routine that can sit alongside any OCD care you already receive.
“Get my finances under control” is a lot to ask of one sitting. Choose a smaller action instead: pay one bill, review this week’s transactions, or decide whether a planned purchase fits the amount you have set aside for it. Before you begin, write down what completing that action involves.
For a bill, that might mean confirming the amount and due date, submitting the payment, and saving the confirmation once. A short definition helps you recognize when you have done the practical work, even if you do not feel fully settled. It also keeps one task from expanding into a search through every account and every possible future problem.
Checking a payment detail before you submit it is useful. Reopening the same confirmation repeatedly to feel completely certain may keep the worry active without adding information. The difference is not always obvious in the moment, so pause and ask what another check would help you do.
| Situation | Useful action | Pause question |
|---|---|---|
| A bill is due | Confirm the amount and due date, then pay it. | Have I completed the payment step I planned? |
| A purchase feels uncertain | Compare the price with the amount available for it. | Am I seeking new information, or repeating a check for relief? |
| A transaction looks unfamiliar | Review its details and contact the financial institution if needed. | Is there a specific unresolved issue that requires action? |
This is a decision aid, not a rule that you must ignore a real problem. An unfamiliar charge, a missing payment, or new information can call for action. If limits on checking are part of your OCD treatment plan, follow your clinician’s guidance rather than replacing it with a limit from a general guide. The International OCD Foundation’s overview of OCD offers background on obsessions and compulsions if you want to learn more.
A regular appointment for ordinary money tasks can reduce the pressure to handle them whenever a worry appears. You might use that time to review upcoming bills, note recent spending, and record any actions that still need attention. Keep the session focused on the tasks you chose rather than trying to resolve every “what if” that comes to mind.
When something needs follow-up, write a concrete next step such as “ask the bank about Tuesday’s transaction.” That is more useful than a note to “make sure everything is okay,” which has no clear finish line. Once you have completed your planned tasks and recorded follow-ups, you can move to the next part of your day. Genuine errors, fraud concerns, and urgent deadlines still deserve timely attention outside a routine.
If you need help with a practical banking or credit question, the Consumer Financial Protection Bureau’s consumer tools can be a starting point. For a major decision, consider speaking with a qualified financial professional about the details that apply to you.
Our OCD & Money Checklist: Taking Control of Your Financial Mindset is a $2.99 printable digital guide for reflecting on OCD and money habits while working toward a calmer routine. You can use a checklist to identify your next practical action and mark what you have finished. You do not have to use it to prove that every decision is risk-free or that all discomfort has disappeared.
Our team sees a useful distinction here: a prompt can help you remember a planned step, while a test can become something you repeat until you feel reassured. If a checklist starts serving the second purpose, you can bring that observation to an OCD-informed clinician. The guide is a companion to everyday organization, not individualized OCD treatment or financial advice.
A workable money decision is sufficiently informed for the situation, not guaranteed to eliminate doubt. For a modest planned purchase, comparing its price with the amount available may be enough to make a choice. A disputed transaction calls for a different action, such as contacting your financial institution. Matching the action to the actual issue helps you avoid treating every uneasy feeling as an emergency.
After you finish a task, try moving to a planned activity even if some discomfort remains. Confidence can grow from practicing a process you can repeat, rather than waiting for a perfectly certain feeling before you stop. If you want a separate resource focused on maintaining routines over time, our Long-Term Growth: Build Habits That Last digital guide is available for $10.99; it is a general habit-building resource, not an OCD-specific tool.
It can help you organize practical tasks and see your next step. It should not become a way to repeat checks until anxiety disappears, and it does not replace OCD treatment.
Look for a specific new issue that needs action, such as an unfamiliar transaction or missing payment. If you need no new information, repeated checking may be worth discussing with an OCD-informed clinician.
No. It is a printable aid for reflecting on money habits and organizing everyday actions, not personalized financial guidance or treatment.

Leave a comment